Corporate Valuation, Investment Management

June 14, 2021

To the Moon or Back to Earth?

RIA Valuations Have Increased Substantially Over the Last Year, but That Doesn’t Necessarily Mean These Stocks Are Overpriced

To the Moon?

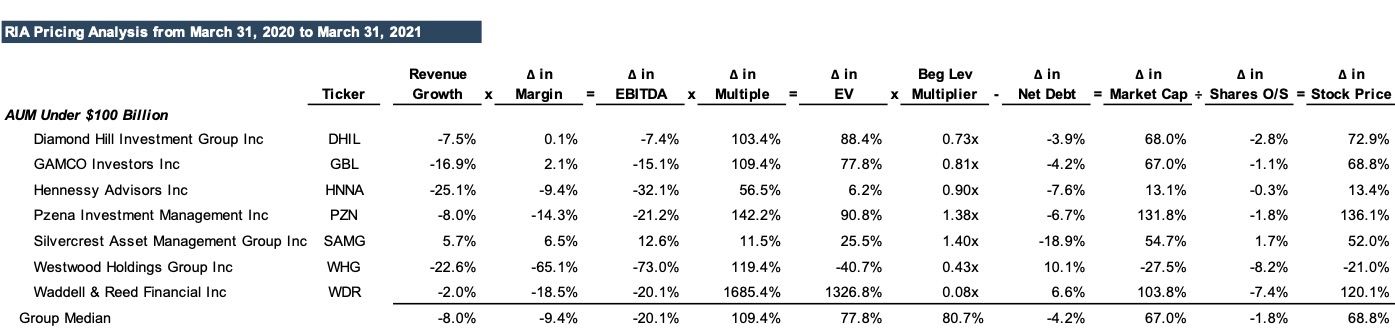
A few weeks ago we blogged about how RIA stock prices have increased over 70% on average over the last year. This rapid ascent begs the question if valuations have gotten too rich with the market run-up during this time. To answer this question, we have to analyze the source of this increase.
Click here to expand the table above

Moving from left to right on the table above, we see that financial performance actually deteriorated over this time – revenue declined and margins compressed, leading to a 20% drop in EBITDA on average for this group of publicly traded RIAs with less than $100 billion in AUM. The increase in the EBITDA multiple more than compensated for the decline in profitability and is the primary driver of the overall increase in value from March 31, 2020 to March 31, 2021. At first glance, a 70% increase in value (when year-over-year earnings have actually declined) suggests that current pricing may be overstretched.

Back to Earth?

When we observe historical levels of RIA valuations, however, we get a much different perspective. Even after the recent run-up, EBITDA multiples are still at the lower end of their historical range. The multiple expansion follows an all-time low for the industry last March when these businesses were trading at 4x EBITDA during the bear market.
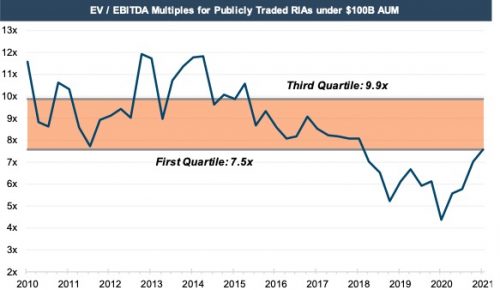
There’s also a logical explanation for the multiple doubling over this period. These multiples are directly related to the outlook for future revenue and profitability, which tend to fluctuate with AUM since management fees are typically charged as a percentage of client assets. AUM balances have risen with the stock market over the last year, so the outlook for future revenue and earnings has rebounded accordingly. Trailing twelve-month (TTM) earnings in March of last year were also suppressed by the bear market’s impact on profitability during the first two quarters of 2020, so a higher TTM multiple is justified when historical earnings lag ongoing levels of profitability. This trend marks a complete reversal of what happened last March when AUM and run-rate performance declined with the market but trailing twelve-month earnings had not yet been impacted. As earnings figures lagged the abrupt price declines, multiples hit all-time lows. Because of this phenomenon, RIA multiples can be especially erratic during volatile market conditions.

Conclusion

While the significant gains in RIA valuations over the last year is fairly alarming, the fundamentals warrant such an increase. The market’s significant rise over the last year buoyed AUM and ongoing profitability, so investors are rationally anticipating higher earnings relative to recent history. Another correction or bear market would certainly reverse this trend, but at the moment, all industry metrics are pointing to the moon.

Continue Reading

Mercer Capital to Sponsor the Association of Trust Organizations 2026 Annual Meeting
Mercer Capital is pleased to sponsor the Association of Trust Organizations’ 2026 Annual Meeting, taking place September 21-23, 2026, at the Grand Hyatt Deer Valley in Park City, Utah. Matt Crow, Brooks Hamner, and Zach Milam will attend on behalf of the firm.The 2026 Annual Meeting is a 1.5-day conference designed exclusively for the trust industry and will feature more than 13 hours of roundtables, panels, and networking. One of the featured sessions is Tuesday afternoon’s Session VI, “What Makes a Trust Company Worth More? Building Value Before the Deal,” which will be moderated by Matt Crow. The panel will explore the factors that drive valuation, how buyers and sellers evaluate opportunities, and what firms can do today to maximize enterprise value.Matt Crow, CFA, ASA, is the CEO of Mercer Capital and leads the firm’s Investment Management Industry team. He works with RIAs, independent trust companies, broker-dealers, and investment consulting firms on valuation matters related to corporate planning and reorganization, transactions, employee stock ownership plans, tax issues, and intangible asset valuations. Matt is also a frequent contributor to Mercer Capital’s RIA Valuation Insights blog.Brooks Hamner, CFA, ASA, is a Senior Vice President and a senior member of Mercer Capital’s Investment Management Industry team. He provides valuation services to RIAs, independent trust companies, asset managers, wealth management firms, broker-dealers, and investment consultants, and he also advises clients buying or selling their business.Zach Milam, CFA, is a Vice President and a senior member of Mercer Capital’s Investment Management Industry team. He has experience in corporate planning and reorganizations, financial reporting, fairness opinions, litigation support, employee stock ownership plans, and estate and gift tax planning and compliance matters.Mercer Capital regularly works with RIAs, independent trust companies, broker-dealers, and other investment management clients on valuation and advisory matters, and the firm looks forward to connecting with attendees in Park City. Visit the conference website to learn more about this year’s Annual Meeting: https://trustorgs.com/annual-meeting/.
The Margin RIA Buyers Actually Underwrite

Why the Post-Closing Cost Structure Matters More Than the Historical Margin

RIA buyers often focus less on a seller’s historical margin than on the earnings the business can generate after closing under the buyer’s operating model. Differences in integration strategy, cost structure, and platform capabilities can lead buyers to underwrite materially different margins and values.
RIA Valuation Insights Blog Investment Management
Read Now about The Margin RIA Buyers Actually Underwrite
Does AI Spending Increase an RIA’s Value-or Just Reduce Its EBITDA?
Does AI Spending Increase an RIA’s Value - or Just Reduce Its EBITDA?
AI investment can create value for RIAs by improving capacity, growth, efficiency, and risk management, but the benefits must ultimately translate into stronger cash flow or reduced risk. Recurring AI costs generally remain operating expenses, making measurable adoption and returns critical to valuation.

Cart

Your cart is empty