Corporate Valuation, Investment Management

March 16, 2021

Common Valuation Misconceptions About Your RIA

Old Rules of Thumb, Recent Headlines, and the Endowment Effect

As a financial analyst, a CFA charter holder, and a generally reasonable person, I know that Zillow isn’t accurate; but as a homeowner, I can’t help myself.  When I am walking around my neighborhood, I always have the Zillow App open, and am speculating about how the “Z-estimate” for my house compares to my neighbors’.  And, of course, my house always is better. Why? Because I own it.  It’s called the endowment effect.  I (as a homeowner) am emotionally biased to believe that something (my house) is valued higher than the market would ascribe, simply because I already own it.

And you, the owner of an RIA, may believe your firm is valued higher than the market value too, and old rules of thumb and recent industry headlines amplify the problem.

Old Rules of Thumb:  Your RIA is Worth 2% of AUM

We have cautioned the use of AUM and Revenue-based multiples before, and an example has proven to be the best way to communicate the unreliability of such metrics.  Consider, Firm A and Firm B, which both have the same AUM.  Firm A has a higher realized fee than Firm B (100 bps vs 40 bps) and also operates more efficiently (25% EBITDA margin vs 10% EBITDA margin).  The result is that Firm A generates $2.5 million in EBITDA versus Firm B’s $400 thousand despite both firms having the same AUM.
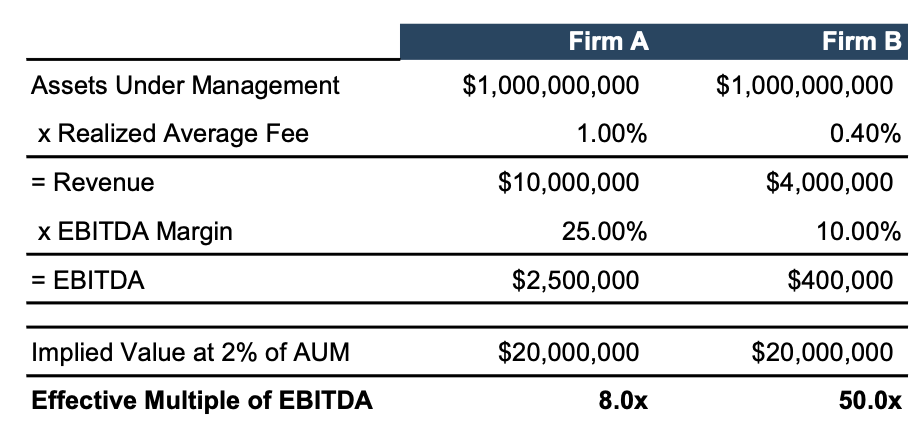
The “2% of AUM” rule of thumb implies an EBITDA multiple of 8.0x for Firm A—a multiple that may or may not be reasonable for Firm A given current market conditions and Firm A’s risk and growth profile, but which is nevertheless within the historical range of what might be considered reasonable.  The same “2% of AUM” rule of thumb applied to Firm B implies an EBITDA multiple of 50.0x—a multiple which is unlikely to be considered reasonable in any market conditions.

Recent Headlines:  Your RIA is Worth 10x EBITDA

Deal activity in the investment management space has been increasing over the last decade as consolidation has increased and outside investors realized the attractiveness of a recurring revenue stream paired with minimal capital investment.  But the headlines touting impressive deal multiples really seemed to pick-up in 2019 with Goldman’s acquisition of United Capital.   However, most of the acquisitions that warrant headlines are of larger investment managers, which due to their sheer scale, are less risky and therefore warrant a higher multiple.

Mixing old rules of thumb, with recent headlines, and the endowment effect typically results in over valuing, which stems from an underestimation of non-systematic risk.

Underestimating Non-Systematic Risk

Most investment managers understand that their firm, like any publicly traded company in their clients’ portfolios, is exposed to systematic and non-systematic risks.  And most seem to understand that investment management firms are subject to certain industry-wide risks such as the move from passive to active investment products and fee compression. But many investment management firms also have significant “firm-specific risks” that make their firm riskier than a much larger investment management firm.  Many small to mid-sized investment management firms suffer from client concentrations, aging client bases, unclear succession plans, a lack of scale, and minimal asset growth (absent market appreciation).

Unfortunately, understanding the value of your RIA is not as easy as applying a multiple to your AUM or run-rate EBITDA.   Value is a factor of cash flow, growth, and risk.  We’ve written a lot about investment management firm valuations:

But, don’t hesitate to give us a call if we can be of assistance.

Continue Reading

Mercer Capital to Sponsor the Association of Trust Organizations 2026 Annual Meeting
Mercer Capital is pleased to sponsor the Association of Trust Organizations’ 2026 Annual Meeting, taking place September 21-23, 2026, at the Grand Hyatt Deer Valley in Park City, Utah. Matt Crow, Brooks Hamner, and Zach Milam will attend on behalf of the firm.The 2026 Annual Meeting is a 1.5-day conference designed exclusively for the trust industry and will feature more than 13 hours of roundtables, panels, and networking. One of the featured sessions is Tuesday afternoon’s Session VI, “What Makes a Trust Company Worth More? Building Value Before the Deal,” which will be moderated by Matt Crow. The panel will explore the factors that drive valuation, how buyers and sellers evaluate opportunities, and what firms can do today to maximize enterprise value.Matt Crow, CFA, ASA, is the CEO of Mercer Capital and leads the firm’s Investment Management Industry team. He works with RIAs, independent trust companies, broker-dealers, and investment consulting firms on valuation matters related to corporate planning and reorganization, transactions, employee stock ownership plans, tax issues, and intangible asset valuations. Matt is also a frequent contributor to Mercer Capital’s RIA Valuation Insights blog.Brooks Hamner, CFA, ASA, is a Senior Vice President and a senior member of Mercer Capital’s Investment Management Industry team. He provides valuation services to RIAs, independent trust companies, asset managers, wealth management firms, broker-dealers, and investment consultants, and he also advises clients buying or selling their business.Zach Milam, CFA, is a Vice President and a senior member of Mercer Capital’s Investment Management Industry team. He has experience in corporate planning and reorganizations, financial reporting, fairness opinions, litigation support, employee stock ownership plans, and estate and gift tax planning and compliance matters.Mercer Capital regularly works with RIAs, independent trust companies, broker-dealers, and other investment management clients on valuation and advisory matters, and the firm looks forward to connecting with attendees in Park City. Visit the conference website to learn more about this year’s Annual Meeting: https://trustorgs.com/annual-meeting/.
The Margin RIA Buyers Actually Underwrite

Why the Post-Closing Cost Structure Matters More Than the Historical Margin

RIA buyers often focus less on a seller’s historical margin than on the earnings the business can generate after closing under the buyer’s operating model. Differences in integration strategy, cost structure, and platform capabilities can lead buyers to underwrite materially different margins and values.
RIA Valuation Insights Blog Investment Management
Read Now about The Margin RIA Buyers Actually Underwrite
Does AI Spending Increase an RIA’s Value-or Just Reduce Its EBITDA?
Does AI Spending Increase an RIA’s Value - or Just Reduce Its EBITDA?
AI investment can create value for RIAs by improving capacity, growth, efficiency, and risk management, but the benefits must ultimately translate into stronger cash flow or reduced risk. Recurring AI costs generally remain operating expenses, making measurable adoption and returns critical to valuation.

Cart

Your cart is empty